Paying in dollars to keep goods from being confiscated is not a complete reform
The new excess-goods clearance procedure may prevent confiscations, but progressive rates and foreign-currency payments shift onto travelers the cost of an economy unable to maintain normal supplies.
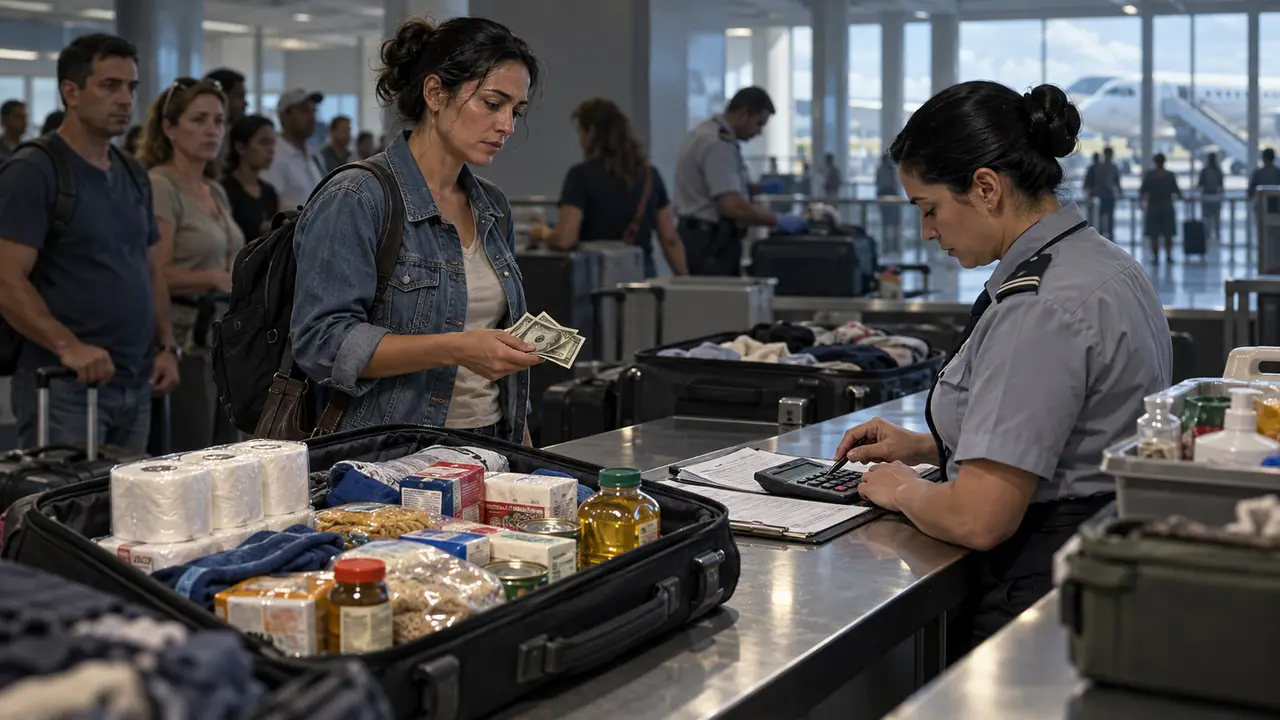
The procedure that took effect on October 12 gives travelers and shipment recipients an alternative for certain goods that exceed noncommercial import limits or are classified as commercial. Instead of confiscation being the only outcome in those cases, the owner may request separate clearance and pay the corresponding charges. The option is real, but it is subject to conditions and does not amount to blanket authorization to import any merchandise.
The change applies after Customs clears the goods admitted under the ordinary rules. A separate process may be opened for the excess if the owner or a representative accepts the procedure. That distinction matters: the new charge does not automatically apply to the entire suitcase, nor does it turn every personal item into commercial merchandise. The authority continues to consider the quantity, value, nature, and frequency of imports.
For travelers, the tax is calculated in brackets: 15 percent on the first $2,000 of value submitted for clearance; 20 percent on the portion above that amount up to $4,000; 25 percent up to $6,000; and 30 percent on the portion above that threshold. The percentages therefore are not applied in full to the total value when the next bracket is reached. Shipments handled under the procedure are subject to a 30 percent rate.
Customs-service charges are added to the tax and may reach $50 for transactions above $6,000. Payment is made with domestic or international cards authorized to operate in dollars; cash is accepted at airports through approved entities. These elements increase the total cost and make it necessary to distinguish the tax rate from the final amount the owner must pay.
The principal practical effect is that payment may prevent the automatic loss of certain goods, not that it guarantees their entry. Prohibitions, special requirements, and measures addressing fraudulent declarations or other violations remain in force. Re-export is also available to those who decline clearance, subject to the established conditions. Administrative measures may apply if neither payment nor re-export is completed under the applicable terms.
The payment currency creates a barrier separate from customs classification. Although the procedure is presented as a regulated way forward, it is available only to people who can obtain dollars or have an eligible card. Its effect may be unequal among travelers: two similar loads may receive the same formal assessment, but whether they can actually keep the goods will depend on each owner’s resources.
The new rate does not eliminate discretion. Customs still determines when quantities, composition, or repetition make an import commercial. If the procedure is to reduce uncertainty, publishing percentages is not enough: assessments must be understandable, criteria consistent, and decisions explained. The available information describes the mechanism and payments, but it does not yet show how individual cases will be resolved.
The reform should be evaluated by the clarity and predictability of its application, as well as by revenue or the number of clearances. It may reduce the likelihood that certain excess goods are confiscated, but it preserves limits and adds a foreign-currency cost. It remains to be seen how often the alternative is used, how heavily the charges weigh on final prices, and whether the rules provide a transparent answer to travelers and families receiving shipments.