A dollar at 800 pesos is the visible price of lost confidence
The new informal benchmark reduces salaries and pensions to a fraction of their value; attacking the quote will not correct the imbalance that produces it.
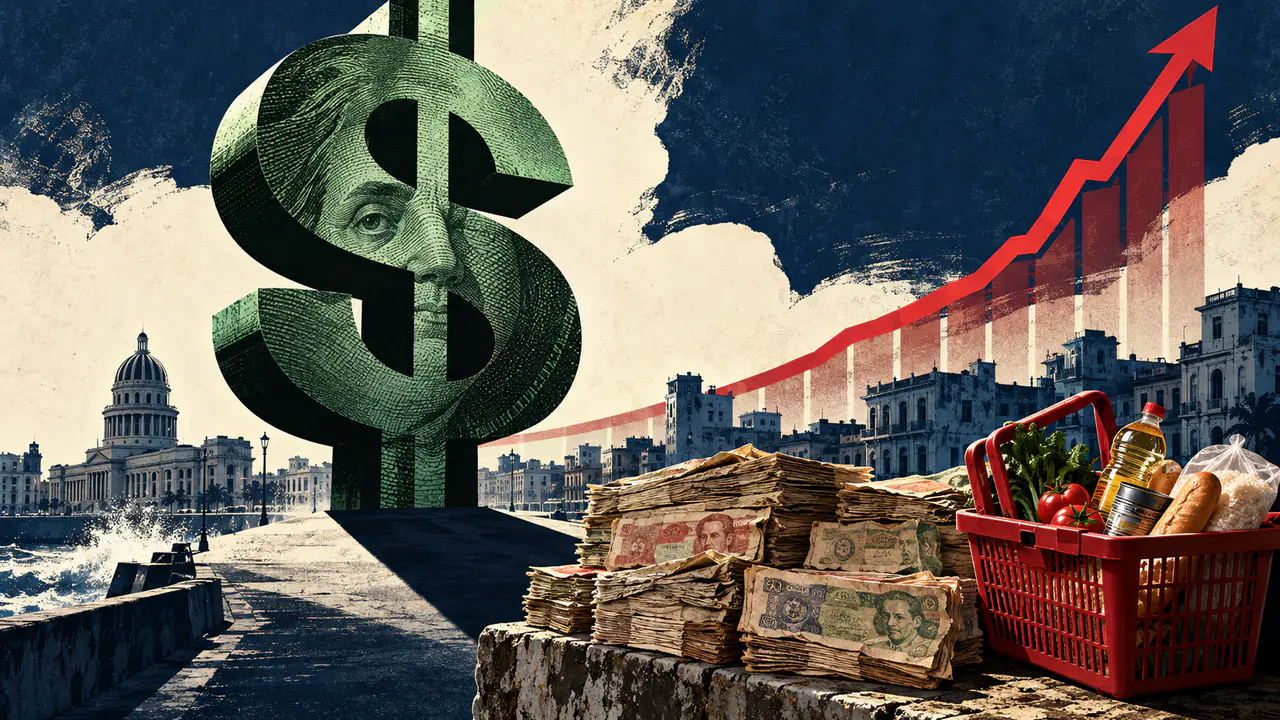
The informal dollar benchmark reached 800 Cuban pesos in October, a level several publications described as a record. It is not an official rate and does not mean every transaction closes at exactly that value. It is a market signal gathered by outlets tracking exchange quotes, useful for observing pressure on the national currency but not a complete record of every transaction.
Published figures do not match at every moment: one update placed the currency at 798 pesos, while later references reported 800 and a higher closing value. The difference may reflect timing and calculation methods; the available material provides no single series reconciling every observation. The central fact is the rise, not uniform precision for every transaction.
For people paid in the national currency, the most direct effect is that more pesos are needed to obtain the same amount of foreign currency at the reference price. The example of $100 equals an outlay of 80,000 pesos in the cited calculation. That conversion helps illustrate the gap but cannot by itself show the cost of everyday goods or the change in each salary.
The connection to household spending requires caution. Sources describe consumer concern and a peso losing ground against foreign currencies, but they provide no detailed measurement of food, transportation or service prices attributable to this quote. It is reasonable to examine the risk of higher costs for people who depend on goods linked to foreign currency; it is not rigorous to present as automatic a relationship the material does not quantify.
The informal quote serves as a benchmark because it reflects exchanges outside the official rate and concentrates expectations about the currency. The collected publications, however, do not fully explain their methodology, the number of observed transactions or national representativeness. The reported record therefore matters as an indicator, but its limits should accompany conclusions about the economy as a whole.
Responses focused only on censoring or discrediting the figure would leave its central question unanswered: why so many actors use foreign currency as a reference. The material documents no specific official measures to change the market and cannot establish which intervention would succeed. It does show that the quote’s rise fuels consumer anxiety and makes peso-denominated income harder to compare with foreign-currency values.
For families, the practical result is greater uncertainty when planning purchases that require foreign currency or whose prices use it as a reference. Available information provides neither comparable household budgets nor enough data on income, pensions and prices. Avoiding unsupported figures matters: one exchange rate alone cannot calculate how much every household loses in daily consumption.
References still need to state clearly the time, method and scope of their calculations, while authorities should publish verifiable information about the currency market and policy. The 800-peso mark summarizes visible pressure, not a complete explanation of its causes. A useful economic discussion must acknowledge the signal, measure its real effects and distinguish perception, observed quote and completed transaction.