Asking the bank is not sending money: what OFAC clarified about Cuba
An update to FAQ 53 separates a customer inquiry from a transfer order. It does not create general permission to send funds to Cuba, but prevents a question from being confused with a blockable transaction.
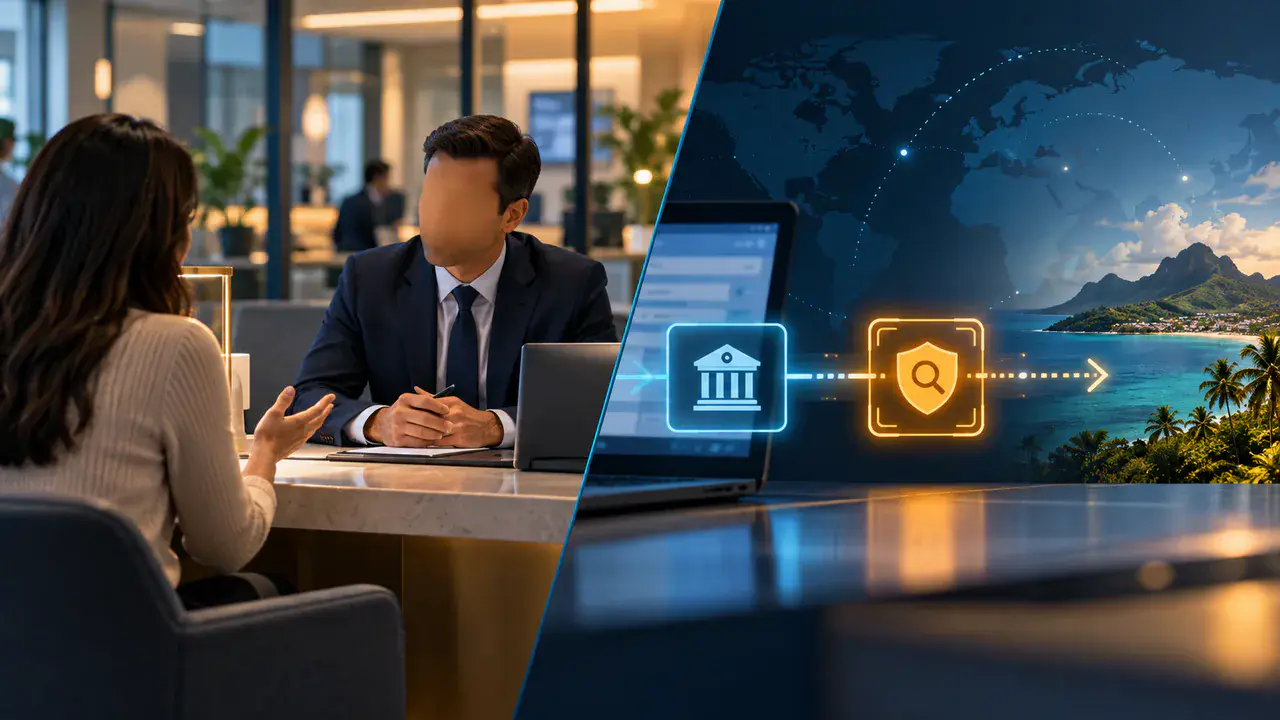
The U.S. Treasury Department's Office of Foreign Assets Control updated its answer to Frequently Asked Question 53 on October 26. The change appears technical but corrects confusion affecting customers and banks: asking whether money can be sent to Cuba is not the same as ordering a transfer.
OFAC uses a direct example. An inquiry such as “can I send money to Cuba?” is not itself a payment instruction. The bank therefore need not treat the question as a transfer to block or reject, or report it as though an attempt to move funds had occurred. The customer is requesting information and has not ordered a transaction.
Blocking and rejecting are also not synonyms. Generally, blocking means immobilizing funds or property in which a sanctioned person has an interest and holding them under control; rejecting means not executing a prohibited transaction that does not require retaining property. The correct response depends on regulations and parties. The update does not change that structure; it clarifies that a simple inquiry occurs before deciding between those actions.
The situation changes when there are concrete transfer instructions and the transaction involves a blocked person or interest in blocked property. The financial institution must then apply the applicable rules—blocking or rejecting as appropriate—and comply with reporting duties. The difference is between conversation and transaction, not between a correct phrase and a forbidden word.
This does not create general authorization for every transfer to Cuba. Sanctions remain, and each transaction depends on sender, recipient, purpose, channel and applicable licenses. A permitted family remittance, authorized commercial payment and transfer to a blocked entity do not receive identical treatment. The FAQ clarifies when a transfer instruction begins; it does not erase the sanctions program.
Nor does it require every bank to offer the same services. Institutions retain risk controls and may decline certain operations even when a customer believes they fit an authorization. That caution explains different answers from two banks in similar cases. A bank's commercial policy is not necessarily an OFAC prohibition, but the practical result can be the same: the money does not move.
For families, the clarification has practical value. Before initiating a transfer, ask in writing what documents the bank requires, which channel it uses, what recipient information it needs and under what authorization it would process the payment. A documented response reduces misunderstandings and distinguishes an internal refusal, an information problem and a legal restriction.
It is also important not to hide or simplify data to help an operation pass. Changing the payment description, splitting amounts or using intermediaries to evade controls can turn a legitimate request into a risk signal. The safest path is to describe precisely who sends, who receives and the funds' purpose, and to retain receipts.
This explanation is informational and not legal advice for a particular case. If a transfer was blocked, rejected or held, the customer should ask the bank for the reason and regulatory reference and consult a professional when appropriate. The update's essence is simpler: a question does not move money. OFAC has now written that asking a bank for guidance should not be confused with executing a transaction.